Wise ways to save on taxes - The Star

Sunday March 21, 2010
Wise ways to save on taxes
By ELAINE ANG and JOSEPH LOH
sunday@thestar.com.my

The tax man cometh again but before you file in your returns, look for ways to maximise your tax savings.

THE time for filing tax returns is upon us again and foremost on every taxpayer’s mind now is how to pay the least tax without being penalised – or even imprisoned – for tax avoidance.
So the million-dollar question is how can Malaysian taxpayers pay less tax?

KPMG tax partner Pauline Tam points us to some simple moves.

“Make an effort to be updated with the full list of tax exempt or partially tax exempt allowances or benefits, personal relief, deduction, rebates or tax incentives that we as individual taxpayers are entitled to.

“Start to recap what you spent in 2009 and compile the receipts for purchase of books, magazines, sports equipment, computer and course fees for a degree at Masters or Doctorate level and so forth that you could have chucked away in your drawers.

(Note : There is also the Housing Loan Interest relief as announced in the Mini Budget which was omitted here)

“If you have somehow forgotten what you spent in 2009, it’s never too late to start planning now for 2010,” she advises.

Peter Lim, a senior manager with a multinational company, has a shoebox full of receipts which he plans to sieve through in the coming weeks to offset against his taxable income.

“I aim to take advantage of all the tax reliefs that I am entitled to. My taxes always result in a big hole in my pocket as I tend to lose my receipts and am not updated on the latest incentives and reliefs.

“Hopefully it will result in lower taxes for me this time especially since the Government did not introduce many new incentives for the year of assessment (Y/A) 2009,” he says.

There are few changes in terms of tax incentives, reliefs and rebates for individual taxpayers for Y/A 2009 versus Y/A 2008.

The main changes consist of the reduction of the top marginal tax rate to 27% from 28%; increase in the rebate given to individual taxpayers whose chargeable income does not exceed RM35,000, to RM400 from RM350; and tax exemption on interest income from Syariah-compliant savings bonds issued by the Government.

The withholding tax rate on non-corporate investors including residents and non-residents for income from real estate investment trusts listed on Bursa Malaysia was reduced to 10% from 15%.

In addition, bonus and directors’ fees are to be taxed in the year such income are received.
Therefore, tips for individual taxpayers to pay less tax would definitely come in handy. (See: Important points to consider and Quick Tips chart)


Employers’ role
KPMG’s Tam says employers might wish to educate their employees on the types of reliefs and tax deductions that they are entitled to, as well as the types of records that employees should maintain to substantiate the claims.

“This would go a long way in assisting employees. The tax awareness programme could involve either inviting Inland Revenue Board (IRB) officials or their tax agents to conduct briefings on a yearly basis or whenever there are tax changes.

“The programme could also include guidance on how to e-file their tax returns and to have a better understanding of their rights and obligations under the tax laws,” she adds.

Employers should also consider the available tax exempt benefits and allowances when reviewing the annual remuneration package for their employees to reduce their financial burden.
However, these would have to be weighed against the additional cost and administrative tasks in implementing the benefits.

PricewaterhouseCoopers Taxation Services Sdn Bhd managing consultant Hilda Liow concurs.
“Malaysian employers are mostly quite receptive to employee tax incentives announced by the Government and do actively consider structuring their employees’ remuneration for tax effectiveness.

“However, the usual constraint is in ensuring that there is no increase of cost to the employer in implementing a tax efficient remuneration structure,” she says.

She stresses that Malaysian employers have to begin to appreciate the overall attractiveness of their employee remuneration and incentives programmes as an important tool for recruiting and retaining talent.

New incentives for Y/A 2010
Incentives that taxpayers should look out for this year are as follows.

Firstly, the top tax rate on chargeable income exceeding RM100,000 is 27% for Y/A 2009, with a reduction to 26% for Y/A 2010.

Secondly, personal relief will be increased from RM8,000 to RM9,000.

In addition, there are new tax reliefs like a tax relief of up to RM500 per year for broadband subscription fees from 2010 until 2012.

The relief for life insurance premiums/approved fund contributions would be increased to RM7,000 from RM6,000.

The additional RM1,000 is given solely to annuity scheme premium from insurance companies contracted with effect from Jan 1, 2010.

The Budget 2010 announcement also saw the unprecedented introduction of a flat reduced tax rate incentive on the employment income of a knowledge worker in a specified economic region (the knowledge worker, qualified activity and specified region must be approved by the Finance Minister).

“The employment income of a Malaysian and foreign knowledge worker residing in Iskandar Malaysia and working in qualifying activities will be taxed at a flat rate of 15%,” Liow explains.
“This incentive applies to knowledge workers applying for and commencing employment in Iskandar Malaysia between Oct 24, 2009 and Dec 31, 2015.”

However, the IRB has yet to issue guidelines on the definition of “knowledge workers” and neither has it provided clear guidelines as to the application process and the documentation to support the application with the Finance Ministry.

To sustain a progressive nation, Liow says the Government would need to enhance the competitiveness of individual taxes.

“There is still the 1% gap between the top personal tax rate of 26% (effective from Y/A 2010) and the corporate tax rate of 25% (effective from Y/A 2009).

“An eventual harmonisation of the top personal and corporate tax rates could provide a competitive advantage in attracting investment and providing greater flexibility for individuals in business to determine their business structure,” she adds.

According to Liow, it is also timely for the Government to expand green tax incentives to the individual consumer especially with the continued focus on green issues and the need for countries to work together to lower their carbon footprint and reduce gas emissions.

Currently, the only incentive enjoyed by an individual is the stamp duty exemption announced in Budget 2010 on the costs incurred to obtain the Green Building Index certificate by the first owner of a residential building.

“More incentives for the individual taxpayer could include residential energy efficient reliefs for energy efficient households, such as the usage of solar heating systems and circulating fans as well as fuel vehicle reliefs for the usage of personal hybrid vehicles,” Liow says.

Tam highlights that widening the income band in each income bracket for the respective progressive tax rates or granting more reliefs or deduction would have a substantial impact in easing the tax burden for individuals.

She reckons the Government could introduce parent relief in recognition of taxpayers supporting their aged and handicapped dependants with further parent relief if the taxpayer lived with the dependant.

“They can also allow taxpayers to claim the full amount of donations given to approved charitable organisations without any restriction. Currently, the deduction of donations is limited to 7% of aggregate income,” she says.

In addition, Tam says, the Government could consider reinstating the deduction of interest paid to finance the acquisition of real property as part of the incidental cost to the acquisition price for computing real property gains tax payable.

For a limited time only, Sunday Star with the assistance of PremierOne Tax Consultants Sdn Bhd. will answer questions from readers who want to know more about filing their tax returns. E-mail your queries to: taxsunday@thestar.com.my

Borang CP500

Many taxpayers received the Borang CP500 in 2010 requesting them to make instalment payments in 2010. This, it seems, is beacuse these taxpayers received other incomes other than employment (eg. rental, dividends, etc) and declared them in "Other Income" column in 2009's Borang B/BE.

Therefore, the instalments payments under CP500 is the tax for these income from 'other sources', which is crazy beacuse 'other income' received in 2008 may vary very differently from the amount received in 2009.

The Star carried a 'clarification' from the IRB on 23 Feb 2010, which raises more questions and does not clarify much actually.

Tuesday February 23, 2010
Get CP 500 notice cancelled if you don’t earn extra income

PETALING JAYA: If you receive a notice of instalment payment (CP 500) from the Inland Revenue Board, do not panic!

The notice, which states the amount, due date and number of instalments, is meant for taxpayers with earnings other than monthly salaries such as income from business and rentals as well as commissions from multi-level marketing or insurance.

Those with a fixed salary, but without other earnings, should go to the branch handling their income tax files to have the notice cancelled.

IRB public relations officer Masrun Maslin admitted that IRB had received many complaints from taxpayers without side income who were issued with such notices.

“Do not panic. If you do not have any other means of income other than your monthly salary, just go to the branch handling your file for the notice to be cancelled immediately,” he said.

However, he said taxpayers would still have to provide supporting documents such as the EA form to show that they did not have income other than their monthly salaries.

Masrun said taxpayers without side income were being issued with such notices due to possible errors in their income tax return forms. “For instance, they must have wrongly put dividends, bonuses or pensions in the other earnings column instead of the salary column.

“The system automatically captures the data on the other earnings and thus, the taxpayers will be issued the CP 500 notices.”

He said previously, the IRB would look at the list of those eligible for the tax liability on other earnings before issuing the notice.

A complainant who declined to be identified said he was upset upon receiving the notice.
He said he contacted the IRB branch handling his file and was advised to ignore it.

However, he was asked to call the branch again next month to check whether he would still have to settle the instalment payments.

“The officer told me that he had been receiving a lot of queries and complaints pertaining to the notice,” he added.

Titles In This Blog

LATEST !


Individual tax

Potongan Cukai Berjadual (PCB) / Schedular Tax Deduction (STD)

Real Property Gains Tax (RPGT)

Others


Q&As

The Malaysian newspapers sometimes run series of Q&As for Income Tax issues. They are compiled as follows :-


Feel free to put your comments here on other topics that might interest you or questions that you want answered.

Can RPGT be minimised ?

By POON YEW HOE

It may be possible by transferring properties to a company, but there are many pitfalls to consider

AT the recently concluded budget seminar of our firm, a major focus of the 650 attendees was the proposed real property gains tax (RPGT) of 5% to be imposed on disposals of property after Jan 1.

Resigned to the inevitability of the tax and the futility of objections, the ingenious ones posed the question to us on the possibility of tax minimisation by transferring their current properties to a company before Jan 1.

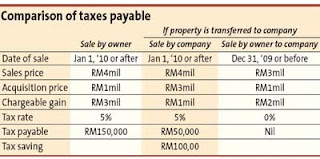
The plan calls for properties which were acquired many years ago at a cheap price (say RM1mil) to be transferred to a company controlled by them at the prevailing market price (say RM3mil).
The transfer will be effected before Jan 1, thus attracting no RPGT on the disposal.

In the future when the property is disposed off by the company, the company will only be taxed on the capital gain over and above the new cost of RM3mil.

If the disposal price by the company is RM4mil, the company will only pay tax on the capital gain of RM1mil (RM4mil less RM3mil) at the rate of 5%, thus resulting in RPGT of RM50,000.
A very ingenious idea indeed.

The comparison of taxes payable shows a tax saving of RM100,000 calculated as seen in the table.

Before anyone embarks on such a potentially lucrative move, one has to bear in mind many of the pitfalls, some of which are discussed below.

Date of disposal

For the purpose of this discussion, the term “chargeable assets” is used to refer to properties and other assets that can be caught under RPGT.

Chargeable assets include shares in real property companies which are companies that predominantly hold assets in the form of properties or shares in other real property companies.

Only chargeable assets disposed on Jan 1 or after will be assessed to RPGT. Those disposed of from April 1, 2007 to Dec 31, 2009 will not. A day is literally night and day for tax purposes!

But the term “disposal date” has a technical definition and it is not the date when the sales price is paid over as we usually consider a sale to be. In sales circles, as they say, a sale is not a sale until the money is collected!

However, for RPGT purposes, a sale is a sale on the day a written agreement is entered into.
Hence, the date that a sale and purchase agreement is entered into for the sale of a property is usually the date of disposal for RPGT purposes. But what if there is no written agreement?

The law provides that the date of disposal is the earlier of two dates – the date that the sales price is fully received or the date that the ownership is transferred. Disposals of this nature may have disposal dates being deferred to a later date, which may fall in the 5% taxable period!

Likewise, disposal dates may be deferred even much later if the sale is dependent on securing approvals from the “Government or an authority, or committee appointed by the Government” – for example, the state government, the Securities Commission (SC) or Foreign Investment Committee.

For these “conditional contracts” which are covered by Para 16 of Schedule 2 of the RPGT Act, the disposal date is when the last of the approvals is obtained.

If a sale and purchase agreement is signed in December 2009 that is subject to SC approval which is obtained in February 2010, the disposal will be treated as having taken place in 2010 and thus subject to the 5% RPGT!

Stamp duty on the transfer

Stamp duty is imposed on the documents for the transfer of title; for example, the memorandum of transfer for transfer of property.

The rates applicable are fairly steep for properties which range from 1% to 3% with the highest rate of 3% being applicable for transfer prices which exceed RM500,000.

Transfers of shares attract duty at the rate of RM3 for every RM1,000 of the transfer price or 0.3%.

However, to avoid stamp duty, one may wish to transfer the property without the transfer of title; for example, the owner holds the property in trust for the company.

What if no transfer of title is effected as in these circumstances? Will the issue of tax avoidance then arise? Perhaps.

Anti-tax avoidance in the RPGT Act

Section 25 of the RPGT Act contains the general anti-avoidance provisions which allow the tax authorities to disregard transactions, vary transactions or impose taxes that should have been imposed.

The law specifies that this right is available if the transactions had the effect of “altering the incidence of tax”, “relieving a person from tax liability” or “evading or avoiding any liability which would otherwise have been imposed”.

Besides these general anti-tax avoidance measures which are also found in the Income Tax Act to discourage income tax avoidance, Section 25 of the RPGT Act also provides for persons who provide loans to related parties; for example, Mr A providing loans to Company A which is owned by him.

The law provides that if Company A sells a property and the property was financed by a loan provided by Mr A, the disposal may be regarded as a disposal by Mr A and not by Company A.

However, the cost of acquisition to Mr A is the market value of the property when Company A acquired the property from Mr A. If Company A had acquired the property from Mr A at the true market value, this anti-tax avoidance provision of the RPGT Act should not pose any problem.

Previous rules by Ministry of Finance (MOF)

A few years ago, the Government had granted a similar tax free period from June 1, 2003 to May 31, 2004.

During that period, the MOF had issued some guidelines to curb the avoidance of RPGT by mandating that any disposal of property must be evidenced by a sales and purchase agreement which must be duly signed and stamped within the exemption period.

Sale of property to a company in exchange for shares .

Care should be taken if the property owner transfers a property to a company controlled by him in exchange for shares, or at least 75% in the form of shares. If the transfer is done this way, the shares may be considered to be chargeable assets.

In the future when these shares are sold, the gains will be subject to the RPGT of 5%. The cost of shares for RPGT purposes is not the par value of the shares but the price paid by the property owner for the property plus incidental expenses incurred by him on the acquisition; for example, legal fees.

As such, if Mr B transfers a piece of property acquired for RM1mil to his company (Company B) at market price of RM3mil in exchange for 3 million RM1 shares, and the shares are subsequently sold for RM4mil, the gains on disposal are calculated at RM3mil which is RM4mil sales price less the acquisition price to Mr B of RM1mil.

Indirectly therefore, Mr B is taxed on his full capital gains and not merely on the gains made by Company B owned by him.

RPGT or income tax?

Another aspect which has deep implications is whether the disposer had held the property as stock-in-trade or as a long term investment.

If held as stock-in-trade, the gains on disposal will attract income tax whereas if held as a long term investment, the gains will attract RPGT.

Some property investments which are disposed as part of a quick sale, or as a single isolated transaction in circumstances which give it a cloak of “adventure in the nature of trade”, could be caught under income tax.

Due to space constraints, we are unable to elaborate on this issue. If these disposals are caught under income tax, what then is the advantage of disposing the properties before Jan 1 if the disposer has to pay income tax at 25% on the gains upfront?

The obstacles can be quite challenging as seen above and careful navigation of the tax law is necessary. But I am sure good tax advisers will find a way out of the conundrum!

· Poon Yew Hoe is a partner of Horwath.

Understanding Real Property Gains Tax (RPGT)

Understanding your tax exposure
By Dr CHOONG KWAI FATT

Exemption order an interim measure to a complete RPGT system

IN Malaysia , real property gains tax (RPGT) is imposed with the intention to curb property speculations. It is imposed on the gains on disposal of Malaysian landed properties and the rate varies from 5% to 30% depends on the holding period.
With effect from April 1, 2007, the Government decided to exempt RPGT in view of the economic slowdown and it was aimed at assisting property developers in disposing of their houses, and spearheading the economic progress.

Prime Minister Datuk Seri Najib Tun Razak, who is also Finance Minister, on Oct 23, however, reintroduced RPGT to put in place a fair administration of taxes.

In a nutshell, an equitable system will now be in place as income tax are imposed on income derived by any person in Malaysia while RPGT, on capital gains on disposal of landed properties. There will not be any loss of revenue to the Government.

In the Budget 2010 speech, the Government’s intention was clear. It is to ensure that the Malaysian tax system is equitable and continue to be able to generate revenue for development purposes. In line with this, the Government proposed that a tax of 5% be imposed on gains from the disposal of real property from Jan 1 2010. Any agreements signed between now till Dec 31 remains RPGT exempted.

Finance Minister II Datuk Seri Ahmad Husni Mohamad Hanadzlah then, exercising his power under section 9(3) of the Real Property Gains Tax Act 1976 (RPGTA), gazetted Real Property Gains Tax (Exemption) Order 2009 which will take effect from Jan 1, 2010.

A fixed RPGT rate of 5% on gains from property gains is achieved through the application of this exemption order.

Malaysian individuals are accorded tax exemption of 10% of the chargeable gain (CG) from the computation of RPGT3. Thus, this would effectively mean that they will be paying less than 5% of RPGT rate while companies continue to pay 5%.

The RPGT Exemption Order exempts any person from the application of Schedule 5 of the RPGTA on the payment of tax on the CG arising from any disposal of assets on or after Jan 1, subject to the condition that the amount of CG exempted shall be determined in accordance with the following formula: A/B x C where:

A = Tax on CG at the appropriate tax rate reduced by the Tax on CG at 5%;
B = Tax on CG at the appropriate tax rate;
C = Amount of CG

Effectively, the exemption formula can be simplified as follows:
Chargeable gain x (Appropriate rate – 5%) / Appropriate rate

The appropriate tax rate to be applied on this exemption order depends on the holding period of the property which is summarised as perTable A.

Illustration: Malaysian citizen individuals

Chia Lat acquired a condominium in Bangsar for RM500,000 on Jan 1, 2008. On March 31, 2010 he decides to dispose the property for RM780,000. The RPGT to be paid by him would be as per Table B.

Illustration: Companies

Using the same example as above, and assuming the taxpayer is a Sdn Bhd, the RPGT payable would be as per Table C.

Mathematical confusion

The mathematical formula stipulated in the RPGT exemption basically restores to the fact that the RPGT is 5% on the CG. This is the mathematical equation:
Assuming the appropriate tax rate is y and CG is x, then the RPGT payable after the RPGT exemption would be :

[x – x(y - 5%)/y ] y =xy – xy + 5% x
= 5% of x

The Government has stated that the purpose of the RPGT is to have a fair administration of taxes. Thus the exemption is an interim measure to begin with RPGT of 5% taxes. In years to come, once the exemption order is revoked, RPGT payable would revert to the original position, ranging from 30% to 5%, depending on the holding period.

Policy reform: Currently, taxpayers are only required to keep accounting records for seven years under the law. It may not be feasible to impose 5% on the chargeable gain on gains derived from holding periods more than seven years. This would mean tax payers are required to keep their accounting records for an indefinite time to justify cost attributable to the acquisition.

It is therefore suggested that the Government impose 2% on selling price instead of holding periods exceeding seven years or as in the past, exempt these gains from RPGT. After all, the underlying purpose of RPGT is to curb speculation of properties rather than tax collection.

Moving forward, the Government may likely further align the taxes on landed transactions to be equitable with the income tax system. Therefore, it is crucial that the rakyat understand the Government’s overall objectives and appreciate that this exemption order is an interim measure to prepare the country for a complete restoration of the RPGT system when the time comes.

Once the country’s economy is paced and sustaining desired growth, this exemption may likely to be revoked and property gains will be back causing gains will be taxed at the appropriate rate.
Till then, this exemption order will continue to allow us to enjoy most of our short-term trading gains from real property transactions.

● Dr Choong Kwai Fatt is deputy dean, Research and Development, Faculty of Business and Accountancy, University of Malaya .

RPGT only for sales within 5 years of purchase

The following is an extract of a report in The Star newspaper on 24 December 2009.

PUTRAJAYA: The real property gains tax (RPGT) announced during the 2010 Budget will now only apply to property sold less than five years from its purchase, Datuk Seri Najib Tun Razak said.

The Prime Minister said the 5% tax would now only be imposed on property sold within five years of the date of purchase.

He said the decision would cause the Government to lose about RM200mil in revenue, adding the move was made following appeals from the Federation of Chinese Associations of Malaysia (Hua Zong) and the business sector.

“This was also decided upon as the Government wants to see a stronger growth in the property sector next year. We are willing to forgo a substantial amount of revenue so that the sector can expand and grow.

“The property sector has shown signs of improvement but we feel that it requires further impetus so that it can continue to grow from strength to strength.

Q&A with Deloitte Malaysia on 2010 Budget

Deloitte Malaysia 's Q&A on Budget 2010
by Financial Daily on Tuesday, 27 October 2009 03:40

KUALA LUMPUR: Following the tabling of Budget 2010 last Friday, Deloitte Malaysia worked together with The Edge Financial Daily to enlighten readers on how the various proposals would impact tax payers and consumers. The following are the answers provided by Janice Tan and Lee Chong Hoo of Deloitte Malaysia based on queries sent in by our readers.

Question 1: What is the impact on a worker earning, say, RM5,000 per month pursuant to Budget 2010?

A: He would not benefit from the proposed one percentage point reduction in the personal income tax rate from 27% to 26% as his chargeable income does not exceed RM100,000.

However, he would be entitled to claim the following additional/new tax reliefs proposed:-
• additional personal relief of RM1,000 (an increase from RM8,000 to RM9,000);
• additional relief of RM1,000 for premium paid on annuity scheme from insurance companies (please refer to further details in our answer to question 2 below);
• new relief on broadband subscription fee paid of up to RM500 per year for years 2010 to 2012.

Q2: How does the proposed additional relief of RM1,000 for premium paid on annuity scheme work and what annuity scheme will it encompass?

A: The additional relief of RM1,000 is in respect of premium paid on annuity scheme from insurance companies contracted from Jan 1, 2010 or additional premium paid on existing annuity scheme from Jan 1, 2010.

This is on top of the existing relief for premiums paid on life insurance or annuity scheme and contributions to the Employees Provident Fund (EPF) of RM6,000.

Where the premium paid on the new annuity scheme or the additional premium paid on existing scheme exceeds RM1,000, the excess can be claimed against any unutilised amount for the existing relief of RM6,000, subject to a cap of RM7,000 for the aggregate amount claimed.

The annuity scheme for the purposes of the above relief under Section 49(1) of the Income Tax Act 1967 (ITA) is an annuity scheme contracted for with an insurance company for securing on death a deferred annuity and not the existing annuity purchased through EPF Annuity Scheme. Currently, a separate relief of RM1,000 is given for the premium paid on the EPF Annuity Scheme under Section 49(1C) of the ITA.

Q3: I understand that Real Property Gains Tax (RPGT) will be reinstated from Jan 1, 2010. Is the 5% tax rate as announced in the budget a fixed rate regardless of the holding period of the properties? Will this just apply to an individual?

A: Notwithstanding the proposals in the Finance Bill, the Ministry of Finance has confirmed that a 5% rate of RPGT irrespective of the holding period and category of tax payers, ie whether individuals or companies, will be introduced through a Ministerial Exemption Order effective Jan 1, 2010.

Q4: I have an apartment under the joint names of my son and myself. I wish to change the ownership in the apartment to either be:-
a) jointly owned by my daughter and myself, or
b) solely owned by my daughter.
Will the above proposed transfers be subject to RPGT based on the Budget 2010 proposals?

A: The transfer of ownership from yourself to your daughter under (b) will be regarded as a gift between parent and child and thus will be exempted from RPGT.

However, the above exemption by way of gift does not cover the transfer of ownership from your son to your daughter. Your son may choose to exercise the once-in-a-lifetime exemption from RPGT for disposal of private residence.

Q5: What will be my obligations if I were to acquire a property after Jan 1, 2010 for a total consideration of, say, RM500,000?

A: You would need to withhold the lower of the amount of money consideration or 2% of the total consideration and remit the sum to the Inland Revenue Board (IRB) within 60 days from the date of disposal. Assuming the total consideration of RM500,000 consists wholly of cash, the amount required to be withheld and remitted would be RM10,000. In addition, you would also be required to submit a return on acquisition of chargeable asset under the existing requirement of the RPGT Act 1976.

Q6: Will my obligation be different if my purchase consideration is partly in cash, say, RM5,000 and the balance is paid by way of shares?

A: The amount required to be withheld and remitted to the IRB will be reduced to the whole amount of the money consideration of RM5,000 and not 2% of the total consideration.

Q7: What will happen if I do not fulfil my obligations as an acquirer under the RPGT Act?

A: Failure to comply with the above withholding requirement would result in a 10% penalty to be imposed on the acquirer and the withholding due plus the penalty would be regarded as a debt due from the acquirer to the government.

Q8: If I sell two properties, one at a profit of RM50,000 and another at a loss of RM15,000 in the same year, what is my chargeable gain?

A: It is proposed under Budget 2010 that any allowable loss arising from a disposal of a chargeable asset would be deducted against any chargeable gain arising from subsequent disposals. As such, your chargeable gain would be RM35,000 after deducting the allowable loss of RM15,000.

Q9: Currently I have two credit cards, one from Citibank and the other from CIMB. I am the principal card holder while my wife and two children are secondary card holders from both banks. I heard that I will be imposed a service tax on such cards effective from Jan 1, 2010. How will it affect me?

A: Effective from Jan 1, 2010, service tax of RM50 and RM25 would be imposed annually for each principal and secondary card respectively. As such, you would be subject to service tax totalling RM250 annually [(RM50 x 2) + (RM25 x 3 x 2)] for the above principal and secondary cards

Q10: I understand that tax incentives for health tourism would be enhanced whereby the exemption rate of 50% on the value of increased exports would be increased to 100% subject to 70% of the statutory income for each year of assessment? How does the exemption work and what would constitute exports for the purposes of the above exemption?

A: The amount of income to be exempted is computed based on the increase in the value of qualifying services exported for two consecutive basis periods.
Assuming the values of services qualifying for exemption are RM100,000 and RM200,000 for Year 1 and Year 2 respectively, the value of increased exports would be RM100,000 ie (RM200,000 — RM100,000).

As such, the amount of income to be exempted for the above example under the Budget 2010 proposal would be RM100,000 instead of RM50,000 based on the existing 50% exemption rate.
The above amount exempted would be allowed as a deduction against the person’s statutory business income (SI) in arriving at the chargeable income but is restricted to 70% of the SI for that year of assessment. Any unutilised amount can be carried forward to be deducted against future statutory income. Normally, statutory business income is computed by deducting allowable expenses and capital allowances from the gross income of the business.

To qualify for the aforesaid exemption, the healthcare services must be provided to the following foreign clients in Malaysia :

a) A company, a partnership, an organisation or a cooperative society incorporated or registered outside Malaysia ;
b) Non-Malaysian citizens who do not hold Malaysian work permits; or
c) Malaysian citizens who are non-residents living abroad.

For the purposes of the enhanced incentive, foreign clients would now exclude:

a) A non-Malaysian citizen that participates in Malaysia My Second Home Programme and his dependents;
b) A non-Malaysian citizen holding a Malaysian student pass and his dependents;
c) A non-Malaysian citizen holding a Malaysian work permit and his dependents; or
d) Malaysian citizens who are non-residents living abroad and his dependents.

However, healthcare services providers who are currently providing services to foreign clients who are excluded under the enhanced incentive can continue to enjoy the existing incentives.

This article appeared in The Edge Financial Daily, October 27, 2009.